Tags: MiTek / Marmon / Warren Buffett
This fanpage is not officially affiliated with Berkshire Hathaway: Disclaimer
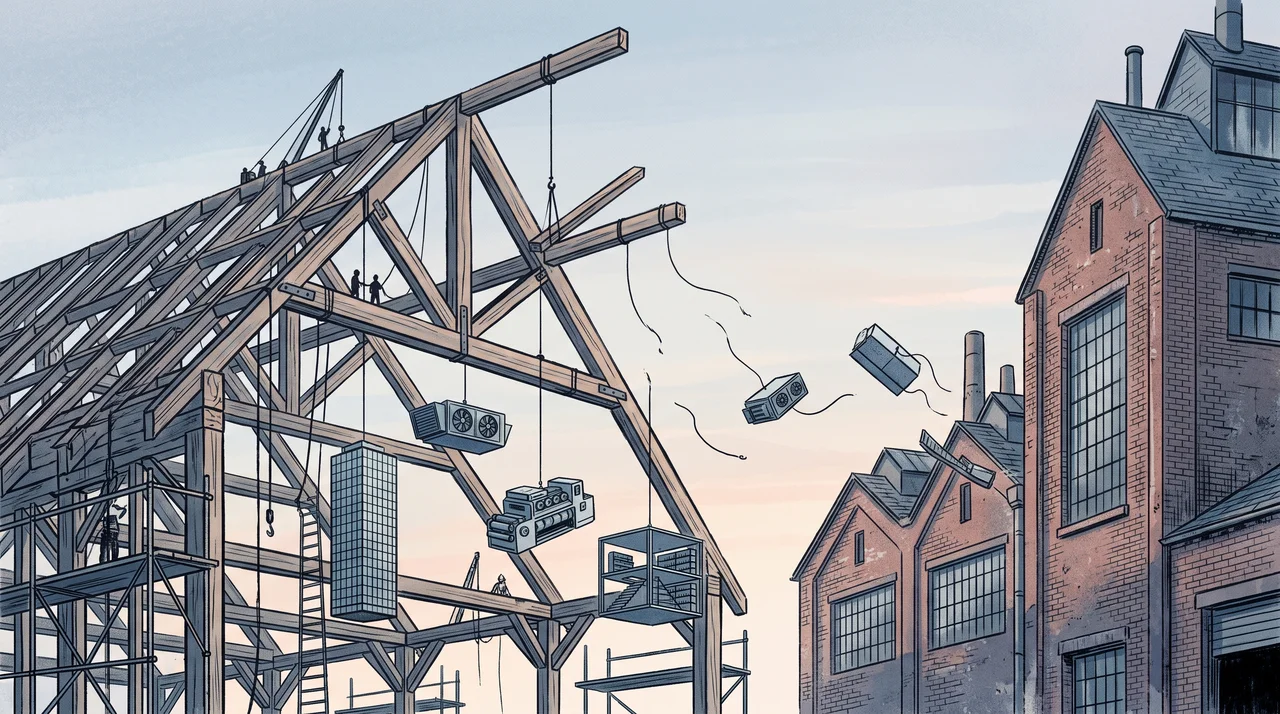
In the summer of 2001, fifty-five managers of a St. Louis truss-plate company each wrote a cheque for at least $100,000 to buy into the business they already ran, and many of them borrowed the money to do it.1 They paid exactly what Berkshire Hathaway paid, $10,000 a share. Five years later Warren Buffett told shareholders those shares were worth $71,699, that the company had made fourteen acquisitions and still paid off its loan from Berkshire, and that it would be "embarrassing" if its stock price passed Berkshire's own.2 That company was MiTek, and by 2004 Buffett was calling it a "mini-Berkshire."3 (Not to be confused with Markel, the insurer long nicknamed the "baby Berkshire," whose stake Berkshire has since unwound.↗) What follows is what became of the mini-Berkshire, reconstructed from twenty-five years of Berkshire's own filings. It grew into nuclear-grade HVAC, curtain walls for skyscrapers and machinery for battery factories. Then, in 2021, that conglomerate was quietly unwound. MiTek itself is still a Berkshire company, but the largest single destination for the pieces it shed was another Berkshire subsidiary. The episode shows how narrowly Berkshire's most famous promise is drawn. The pledge never to sell a good business holds for what Omaha buys, and it does not reach what its subsidiaries buy.
The Deal Was Built to Make Managers Feel the Cost of Capital
The connector plate that arrived in Buffett's mail in spring 2001, a stamped piece of steel that holds the timbers of a roof truss together, is the familiar part of the story, and it needs only a sentence. MiTek's chief executive Gene Toombs mailed one with a letter, Buffett phoned him, and "it took me only a minute to realize that he was our kind of manager."1 The more interesting part is the structure Berkshire built around the managers who came with the plate.
MiTek's British parent, Rexam, had refocused on aluminium cans and would not fund the acquisitions Toombs and his team wanted to make.4 Berkshire bought 90% of the company on July 31, 2001,5 and the way it paid was unusual. Of the $420 million total, Berkshire lent MiTek $200 million at 9% and bought $198 million of stock; the 55 employees bought 2,200 shares for the remaining $22 million.2 That arithmetic gives Berkshire 19,800 shares against the managers' 2,200, a clean 90/10 split, and it put a 9% coupon on nearly half the purchase price. Buffett spelled out the point of the design in the 2001 letter. Unlike option holders, he wrote, these managers "face the downside of decisions as well as the upside. They incur a cost of capital. And they can't 'reprice' their stakes."1
That is the first thing worth noticing about MiTek. It was set up from day one as a company with an appetite for acquisitions, owned by people who had borrowed to own it and carrying a 9% loan from its new parent. Toombs had come to Berkshire precisely because his previous owner would not finance deals. A buyer who would was always going to get a roll-up.
The Roll-Up Repaid Its Own Purchase Loan
It did. By the 2006 letter MiTek's sales had tripled, it had made 14 acquisitions at a cost of $291 million, and it had nevertheless "paid off its debt to Berkshire and holds $35 million of cash."2 The per-share value had gone from $10,000 to $71,699, a multiple of 7.2 in five years, or roughly 48% a year compounded. Over the five calendar years 2002–2006, Berkshire's own book value per share grew 1.85 times and the S&P 500 returned 1.35 times.6 The periods are offset by about six months and the measures are not identical, but the gap is too wide for either caveat to close.
Buffett noticed. "Gene Toombs has delivered results from these deals far in excess of what he had predicted," he wrote in the same letter, adding: "In effect, we leverage the managerial talent already with us by these tuck-in deals. We will make many more."7 MiTek kept its side of that sentence through the housing crash. In the 2010 letter, with Berkshire's housing-linked businesses earning $362 million against $1.3 billion in 2006 and their payrolls down by about 9,400 people, Buffett reported that MiTek had "made, or committed to, five bolt-on acquisitions during the past eleven months."8 By the 2011 letter the count since 2001 was 33 tuck-ins, "almost all successful,"9 and by early 2014 MiTek's chief executive Tom Manenti put it at more than forty.4
The machinery behind that pace was itself a small Berkshire. According to Lawrence Cunningham's account, MiTek ran a central M&A function with one executive responsible for finding and vetting targets. Its senior managers were "not necessarily required to clear acquisitions ahead of time" with Omaha, and its chief executive kept Buffett informed by monthly written notes and a phone call for anything unusually large.4 Berkshire had bought a manager, and the manager had built an acquisition department.
By 2017 a Truss-Plate Maker Was Selling Nuclear Air-Conditioning
The early deals stayed close to the plate: connectors, truss machinery, design software. USP Structural Connectors, bought from Gibraltar in 2011, was a long-standing distribution partner brought in-house.4 But from 2008 the roll-up moved into the commercial building, and from there into things that had nothing to do with roofs at all. The table below is a selection of the deals, each paired with what eventually became of it.
| Bought | Business | What it added | What became of it |
|---|---|---|---|
| 2008 | Hohmann & Barnard | Masonry and stone anchors | Moved to Marmon, 20211011 |
| Dec 2008 | Aegis Metal Framing (joint-venture buyout) | Cold-formed steel trusses (Ultra-Span) | Renamed MiTek, 20211213 |
| Jun 2009 | SidePlate Systems | Steel-frame connection engineering | Folded into the MiTek brand, 20211415 |
| 2009 | Heat-Pipe Technology | Dehumidification and energy recovery | Listed as sold, 2021; the heat-pipe line now appears in Marmon's description1611 |
| Jul 2013 | Benson Industries | Curtain walls for high-rise buildings | Key assets sold to Permasteelisa, Jan 20251718 |
| Nov 2013 | Cubic Designs | Mezzanines and work platforms | North American mezzanine operations sold to Steele Solutions, Jan 20251920 |
| Apr 2014 | Ellis & Watts | Nuclear-safety HVAC systems | Moved to Marmon, 20211911 |
| Feb 2015 | M&M Manufacturing | Ventilation ductwork | Moved to Marmon, 20211911 |
| By 2017 | TBS Engineering (UK) | Machinery for lead-acid battery plants | Moved to Marmon, 2021; sold by Marmon to Rosendahl Nextrom, 2026211122 |
| Jan 2020 | Hornet Saw Systems | Truss-plant saws | Residential core19 |
| May 2026 | Acer Lumber Retrieval Systems | Truss-plant lumber handling | Residential core23 |
By the 2017 Form 10-K, Berkshire described MiTek as operating in three markets: residential, commercial and industrial. The industrial arm included "automated machinery for the battery manufacturing industry," "design and supply of Nuclear Safety Related HVAC systems and components," custom air handlers, and prefabricated mezzanines for warehouses. The filing gave the reason in a single clause: the bolt-ons were "intended to diversify product offerings and reduce the impact of the cyclical global housing markets."21 MiTek sold in more than 100 countries and had offices or plants in 21 of them.21 In both the 2017 and 2018 letters, Buffett ranked it among the "next five" of Berkshire's largest non-insurance businesses, a tier that earned $2.1 billion and then $2.4 billion pre-tax.24
The diversification logic was Berkshire's own logic applied one level down. A business exposed to a single cycle buys businesses exposed to other cycles, and the parent's balance sheet smooths the result. Nobody at MiTek needed permission to do it.
A New Chief Executive Read the Map Differently
In January 2017 MiTek named Mark Thom chief executive. He was an outsider, sixteen years at Tyco Healthcare and then a leadership consultant to MiTek's senior team. Manenti became executive chairman for the year and, the trade press noted, "will continue to report to Warren Buffett."25 The 2018 Form 10-K carried the first sign of what came next: MiTek "commenced reorganizing efforts in 2019 to focus on a 'One MiTek' brand, operating as one global company operating in two sectors, residential and commercial," which was "expected to provide customers with more targeted solutions and produce a more simplified, efficient and better-integrated organizational structure."26
Two sectors, not three. In the 2019 10-K the industrial market is gone from the opening sentence of MiTek's description, although the businesses themselves were still MiTek's and would stay so for two more years.27 In the 2019 letter Buffett's "next five" are Berkshire Hathaway Automotive, Johns Manville, NetJets, Shaw and TTI, and MiTek is off the list.28 The filings do not say why. Its earnings fell out of that tier while it still owned every unit, so the reorganisation was a response to something, not the cause of the slip. In May 2021 Thom folded Benson, SidePlate and Ultra-Span into the single MiTek name, calling it "part of what has been a multi-year journey for us, following a period of acquisitions beginning in 2008."14 It was a polite description of a strategy being reversed. Under Toombs and Manenti, MiTek had often bought standalone businesses and left them standalone, and Cunningham names USP, Benson, Hohmann & Barnard and Heat-Pipe as "autonomously operated."4 Under Thom it was integrating the businesses that fitted and finding homes for the ones that did not.
The Handoff to Marmon Shows Only in the 10-K Text
Where those homes were is the part nobody announced. MiTek's newsroom lists no release about it,19 and the 2021 shareholder letter does not mention it. The evidence is in two places a shareholder would have to go looking for.
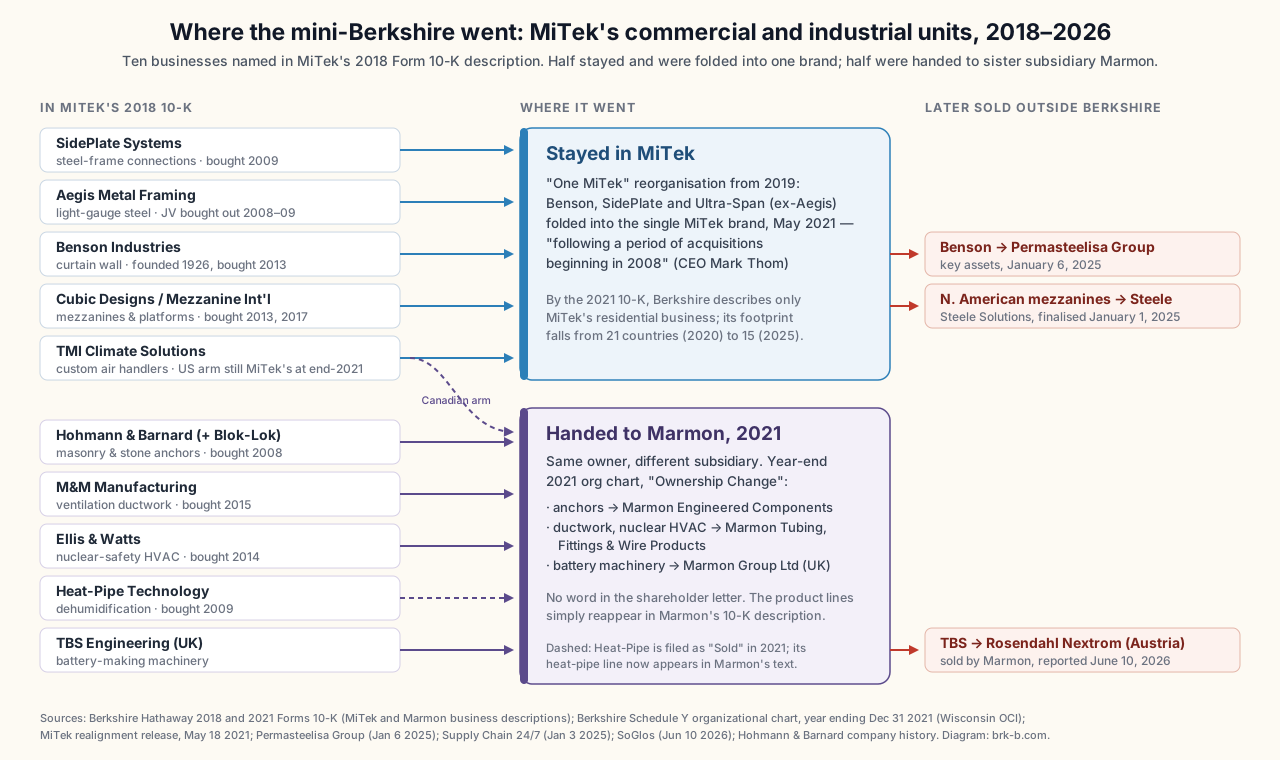
The first is an organisational chart Berkshire files with insurance regulators. Its chart for the year ending December 31, 2021, filed with the Wisconsin Office of the Commissioner of Insurance, lists under "Ownership Change": Hohmann & Barnard and its Canadian affiliate Blok-Lok, now "owned by Marmon Engineered Components Company"; Ellis & Watts and M&M Manufacturing, "owned by Marmon Tubing, Fittings & Wire Products"; and TBS Engineering, "owned by Marmon Group Limited."11 Hohmann & Barnard's own history page puts it plainly: in 2021 "MiTek Industries, Inc. divested the company to Marmon Holdings, another subsidiary of Berkshire Hathaway."10
The second is the text of the 10-K itself, which moves the product lines from one paragraph to another between 2020 and 2021 without a word of explanation.
| Product line | 2020 Form 10-K | 2021 Form 10-K |
|---|---|---|
| Masonry anchors | MiTek: "masonry and stone anchoring systems"29 | Marmon Industrial Products: "masonry and stone anchoring systems used in commercial construction"30 |
| Nuclear HVAC | MiTek: "design and supply of nuclear safety related HVAC systems and components"29 | Marmon Plumbing & Refrigeration: "HVAC systems and structures for military, nuclear and medical markets"30 |
| Ductwork and heat pipe | MiTek: "a comprehensive range of ductwork," "energy recovery and dehumidification systems"29 | Marmon Plumbing & Refrigeration: "custom coils ducting, air handling units and heatpipe for the HVAC market"30 |
| Battery machinery | MiTek, 2018 10-K: "automated machinery used by battery manufacturers"26 | Marmon Industrial Products: "equipment for the manufacture and assembly of lead acid batteries"30 |
| Marmon's own HVAC line, for contrast | Marmon Plumbing & Refrigeration: "custom coils for the HVAC market"31 | The phrases above appear in this entry for the first time |
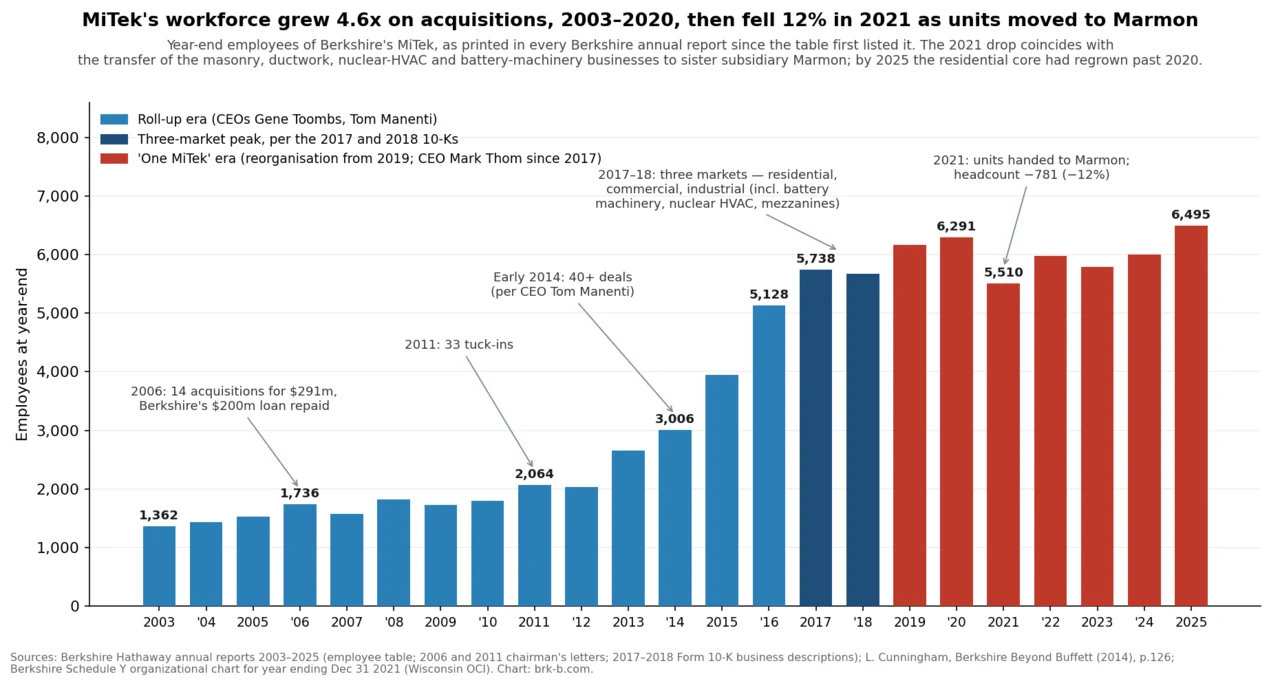
In the same 2021 filing MiTek's own description shrinks to its residential business, though its opening sentence still claims "two separate markets: residential and commercial."32 MiTek's year-end headcount, printed in the employee table of every Berkshire annual report, fell from 6,291 to 5,510 that year, a drop of 781 people or 12%.33
The outside sales came later and in a cluster. On January 1, 2025, Steele Solutions of Wisconsin completed its purchase of MiTek Mezzanine's North American operations, including the Waupaca plant that had been Cubic Designs.20 Five days later Permasteelisa Group announced it had acquired the key assets of Benson Industries, the Portland curtain-wall maker founded in 1926 that MiTek had bought in 2013.18 And in June 2026 Marmon itself sold TBS Engineering, a Gloucester firm with £50 million of turnover, to Austria's Rosendahl Nextrom.22 So by 2026 every business named in MiTek's 2017 industrial segment had left it, for Marmon or for an outside buyer, and of the commercial units only the steel-framing lines, SidePlate and Ultra-Span, were still under the MiTek name.
Permanence Is a Promise Berkshire Makes One Level Up
Berkshire's owner's manual has carried the same sentence for decades: "Regardless of price, we have no interest at all in selling any good businesses that Berkshire owns."34 It is the promise that lets Berkshire buy family companies at prices a private-equity fund cannot match, and MiTek is proof that it is kept. Berkshire still owns MiTek, twenty-five years on.
It is also proof of how narrowly the promise is drawn. It binds Omaha. It has never bound a subsidiary that does its own buying, and nobody pretended otherwise. The same principle also carries a qualifier: the pledge covers "good" businesses, and the filings say nothing about how Benson, the mezzanine plants or TBS performed, so it is possible they were simply the weaker parts of the portfolio. Either way, the sale decision belonged to a subsidiary, not to Omaha. Cunningham notes that when MiTek bought a direct competitor, "there may be no way to make either promise," continuity or autonomy, because the value often lay in eliminating redundancies.4 Benson's owners sold to a Berkshire company in 2013, and twelve years later its assets were sold again. Cunningham chose Benson to illustrate MiTek's deal-making, describing its curtain walls as the kind used on buildings "intended to last for centuries."4
The Marmon handoff is the subtler case, and the more Berkshire-like one. Moving Hohmann & Barnard and Ellis & Watts to a sister company kept them inside the family and put them in a conglomerate built for exactly this kind of orphan, with more than 100 autonomous businesses grouped by industry.35 That is a reasonable thing for a parent to do. It is also a decision about which of its children's businesses fit, which is the kind of central portfolio management Berkshire says it does not do. A subsidiary chief executive cannot move five companies into a sister conglomerate on his own authority, and the filings do not say who proposed it. They do say who was in the chair. Since 2018 both MiTek and Marmon had sat under Greg Abel's oversight as Vice Chairman of Berkshire's non-insurance operations, while Buffett kept "major capital allocation and investment decisions."39 Whatever either man thought of the handoff, neither wrote about it.
The Mini-Berkshire Survived, Narrower
None of this makes MiTek a failure. Its headcount at the end of 2025 was 6,495, above the 2020 peak, even though residential is now the only business Berkshire's 10-K bothers to describe.33 Headcount measures scale, not profit, and Berkshire has never published MiTek's earnings on their own; the last public signal of those was its place in Buffett's "next five" in 2018.24 It still buys bolt-ons: in May 2026 it acquired Acer Lumber Retrieval Systems, a long-time partner whose lumber-retrieval system plugs into MiTek's own MatchPoint machinery.23 What it no longer does is wander. Its footprint has narrowed from offices in 21 countries in 2020 to 15 in 2025, and from sales in more than 100 countries to more than 60.36 Both of the post-2019 bolt-ons in the newsroom, Hornet Saw Systems in 2020 and Acer in 2026, serve the same customer, the factory that makes roof trusses.19
The lesson for Berkshire's present is about who does the consolidating. When Greg Abel announced the Taylor Morrison deal, he said Berkshire expects "over time" to "unify our site-built homebuilding operations into a combined platform."37 The completion release of July 24, 2026 made it concrete: Taylor Morrison's chief executive Sheryl Palmer will oversee its integration with Clayton Properties Group, Berkshire's collection of 15 regional homebuilders.38 This site flagged that as a break with the hands-off tradition.↗ MiTek suggests the break is smaller than it looks. In 2021, with Abel overseeing both companies, Berkshire was already moving businesses from one subsidiary to another. The difference is that the 2021 version was never announced, and its results were filed in places few shareholders read. Marmon, which took in MiTek's orphans, is a natural receiver for the next set.↗ Justin Industries, which Berkshire split on day one and then left alone, is the textbook version of hands-off ownership. MiTek is the other version: hands off for twenty years, until the parent's own people decided where the pieces belonged.↗
In 2006, describing a truss-plate maker that had started buying everything near a building site, Buffett wrote: "MiTek … is developing into a mini-conglomerate. At the rate it is growing, in fact, 'mini' may soon be inappropriate."2 He was right about the word, though not in the way he meant. The deals that took MiTek into masonry anchors, curtain walls and nuclear HVAC all came after he wrote it, from 2008 on. The mini-conglomerate kept growing for another decade, and only then did it shrink back toward the truss plate Buffett had once unwrapped without knowing what it was.
How this article was made: thesis and editing by Anthropic Claude Opus 5.5 with the brk-b.com editor; research, drafting, charts and diagram by Anthropic Claude Opus 5.5, with research assistance from Anthropic Claude Sonnet 5.5; independent review of the draft by Google Gemini 4 Argon; fact-check of every citation against its source by Anthropic Claude Sonnet 5.5.
References
-
Berkshire Hathaway 2001 Chairman's Letter - berkshirehathaway.com — “…we arranged for 55 members of the MiTek team to buy 10% of the company, with each putting up a minimum of $100,000 in cash. Many borrowed money so they could participate.” (p.4) ↩↩↩
-
Berkshire Hathaway 2006 Chairman's Letter - berkshirehathaway.com — “In purchasing MiTek for $420 million, we lent the company $200 million at 9% and bought $198 million of stock, priced at $10,000 per share. Additionally, 55 employees bought 2,200 shares for $22 million… the stock is valued at $71,699 per share.” (2006 Annual Report p.11) ↩↩↩↩
-
Berkshire Hathaway 2004 Chairman's Letter - berkshirehathaway.com — “Gene Toombs, its CEO, has made some brilliant ‘bolt-on’ acquisitions and is on his way to creating a mini-Berkshire.” (2004 Annual Report p.14) ↩
-
Lawrence A. Cunningham, Berkshire Beyond Buffett: The Enduring Value of Values (Columbia University Press, 2014) - cup.columbia.edu, pp.124–127 — “MiTek’s senior managers are not necessarily required to clear acquisitions ahead of time.” ↩↩↩↩↩↩↩
-
Berkshire Hathaway 2001 Annual Report, notes to the financial statements - berkshirehathaway.com ↩
-
Berkshire Hathaway 2006 Annual Report, Berkshire's Corporate Performance vs. the S&P 500 - berkshirehathaway.com ↩
-
Berkshire Hathaway 2006 Chairman's Letter - berkshirehathaway.com (2006 Annual Report p.6) ↩
-
Berkshire Hathaway 2010 Chairman's Letter - berkshirehathaway.com — “At MiTek, we have made, or committed to, five bolt-on acquisitions during the past eleven months” (2010 Annual Report p.14) ↩
-
Berkshire Hathaway 2011 Chairman's Letter - berkshirehathaway.com (2011 Annual Report p.20) ↩
-
Hohmann & Barnard, Our History - h-b.com — “MiTek Industries, Inc. divested the company to Marmon Holdings, another subsidiary of Berkshire Hathaway.” ↩
-
Berkshire Hathaway Schedule Y Organizational Chart for year ending December 31, 2021 - oci.wi.gov — “Hohmann and Barnard, Inc., owned by Marmon Engineered Components Company… TBS Engineering, Ltd., owned by Marmon Group Limited, The” (Ownership Change list) ↩
-
Worthington Industries Sells Share of Aegis Metal Framing Joint Venture - worthingtonenterprises.com ↩
-
MiTek notice: Aegis Metal Framing becomes MiTek, May 2021 - wconline.com ↩
-
MiTek Announces Realignment of Benson, SidePlate and Ultra-Span Structural Framing Solutions - wconline.com — “…part of what has been a multi-year journey for us, following a period of acquisitions beginning in 2008” (May 18, 2021) ↩
-
MiTek Acquires SidePlate - wconline.com ↩
-
Heat Pipe Technology Acquired by MiTek - achrnews.com ↩
-
MiTek Acquires Benson Industries - usglassmag.com ↩
-
Permasteelisa Group Acquires Key Assets from Benson Industries - permasteelisagroup.com (January 6, 2025) ↩
-
MiTek press releases - mitek-us.com ↩↩
-
Steele Solutions expands with MiTek Mezzanine acquisition - supplychain247.com — “The deal, which was finalized on January 1, includes MiTek’s Waupaca manufacturing facility and office staff from New Berlin.” (January 3, 2025) ↩
-
Berkshire Hathaway 2017 Annual Report, Form 10-K Item 1 (MiTek) - berkshirehathaway.com — “MiTek has completed a number of bolt-on acquisitions in the past five years, intended to diversify product offerings and reduce the impact of the cyclical global housing markets.” (p.K-14) ↩↩
-
Acquisition marks exciting new chapter for Gloucester-based global engineering firm - soglos.com (June 10, 2026) ↩
-
MiTek Acquires Acer Lumber Retrieval Systems, Strengthening Automation Leadership - mitek-us.com (May 20, 2026) ↩
-
Berkshire Hathaway 2017 Chairman's Letter and 2018 Chairman's Letter - berkshirehathaway.com (2017 and 2018 Annual Reports p.8) ↩↩
-
MiTek Adds Mark Thom as New CEO - achrnews.com (February 16, 2017) ↩
-
Berkshire Hathaway 2018 Annual Report, Form 10-K Item 1 (MiTek) - berkshirehathaway.com — “MiTek commenced reorganizing efforts in 2019 to focus on a ‘One MiTek’ brand, operating as one global company operating in two sectors, residential and commercial.” (pp.K-15–K-16) ↩
-
Berkshire Hathaway 2019 Annual Report, Form 10-K Item 1 (MiTek) - berkshirehathaway.com (p.K-15) ↩
-
Berkshire Hathaway 2019 Chairman's Letter - berkshirehathaway.com (2019 Annual Report p.6) ↩
-
Berkshire Hathaway 2020 Annual Report, Form 10-K Item 1 (MiTek) - berkshirehathaway.com (p.K-16) ↩
-
Berkshire Hathaway 2021 Annual Report, Form 10-K Item 1 (Marmon) - berkshirehathaway.com — “Industrial Products supplies construction fasteners; masonry and stone anchoring systems used in commercial construction… and equipment for the manufacture and assembly of lead acid batteries.” (p.K-14) ↩
-
Berkshire Hathaway 2020 Annual Report, Form 10-K Item 1 (Marmon) - berkshirehathaway.com (p.K-13) ↩
-
Berkshire Hathaway 2021 Annual Report, Form 10-K Item 1 (MiTek) - berkshirehathaway.com (p.K-16) ↩
-
Berkshire Hathaway annual reports, table of operating businesses and employees: 2003, 2020, 2021, 2025 (all years 2003–2025 in the chart) - berkshirehathaway.com — MiTek: 1,362 (2003); 6,291 (2020); 5,510 (2021); 6,495 (2025) ↩↩
-
Berkshire Hathaway 2010 Annual Report, An Owner's Manual, principle 11 - berkshirehathaway.com (p.99) ↩
-
Berkshire Hathaway 2021 Annual Report, Form 10-K Item 1 (Marmon) - berkshirehathaway.com (p.K-13) — “…a global industrial organization comprising 11 diverse business groups and more than 100 autonomous manufacturing and service businesses.” ↩
-
Berkshire Hathaway Form 10-K Item 1 (MiTek): 2020 (p.K-16), 2023 (p.K-18), 2025 (p.K-17) - berkshirehathaway.com ↩
-
Berkshire Hathaway buys Scottsdale-based homebuilder Taylor Morrison - kjzz.org (June 1, 2026) ↩
-
Berkshire Hathaway Completes Acquisition of Taylor Morrison - taylormorrison.com — “Taylor Morrison to unify with Berkshire Hathaway’s site-built homebuilding operations” (July 24, 2026) ↩
-
Berkshire Hathaway 2021 Annual Report, Form 10-K Item 1A - berkshirehathaway.com — “In 2018, Berkshire’s Board of Directors appointed Mr. Gregory Abel as Vice Chairman of Berkshire’s non-insurance operations… Mr. Buffett continues to be responsible for major capital allocation and investment decisions.” (p.K-24) ↩